Clinical Trials Market Trends, Analysis and Forecasts to 2030
Clinical Trials Market Growth & Trends
The global clinical trials market size is expected to reach USD 78.3 billion by 2030, registering a CAGR of 5.8% during the forecast period, according to a new report by Grand View Research, Inc. An increase in the volume and complexity of clinical trials has been witnessed lately, which plays an important role in the R&D of new drugs and products. The market witnessed a decline of 6% in 2020 owing to the COVID-19 pandemic. However, the market is projected to recover from 2021 onwards. In addition, clinical trials have become increasingly costly, adding to the overall cost of developing a drug.
Clinical Trials Market Segmentation
Grand View Research has segmented the global clinical trials market based on phase, study design, indication, indication by study design, sponsor, service type and region:
Based on the Phase Insights, the market is segmented into Phase I, Phase II, Phase III, Phase IV.
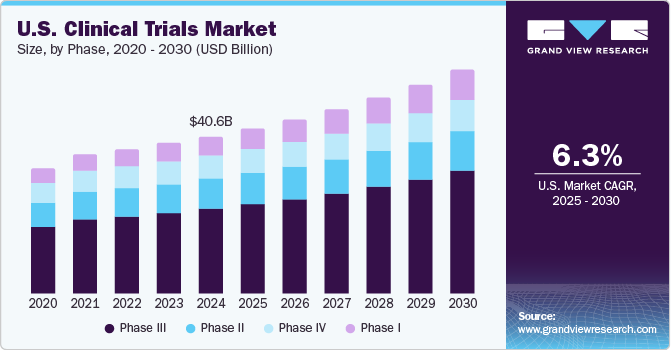
- The Phase III segment accounted for the largest revenue share in 2021, contributing to 53.4% of the global market. This is because Phase III trials are the most expensive and involve huge subjects. The median cost for a single Phase III trial is around USD 19.0 million with 59 new therapeutic agents approved by the FDA from 2015 to 2016. Also, Phase III requires a higher number of patients and often a longer treatment period. The Phase II segment followed in terms of market share accounting for 19.4% in 2021. It is also the second most expensive stage after Phase III. This study is performed in two parts; the first part includes exploring a range of doses along with efficacy studies and the second part includes finalizing the dose.
- Phase II plays a crucial role, especially in oncology-related studies. The FDA estimates that about 33.0% of the medications are usually under Phase II trial. Moreover, there are various therapeutics and vaccines currently in Phase II that are indicated for the treatment of COVID-19, thereby boosting the market growth. For instance, currently, there are 43 therapeutics under Phase II for COVID-19.
Based on the Study Design Insights, the market is segmented into Interventional, Observational and Expanded Access.
- The interventional design segment dominated the market and accounted for the largest revenue share with 45.7% in 2021. It is one of the most prominent methods used in clinical trials. Interventional studies comprised 79.0% of the total registered studies as of May 2020, out of which the majority of studies were for drug or biologics, followed by behavioral, clinical procedure, and device interventional studies. These studies contribute to 94.0% of the total studies that posted results, out of which drug or biologics contribute the most, followed by behavioral, devices, and clinical procedure intervention studies.
- The expanded access trials segment also referred to as compassionate use trials, is anticipated to register a CAGR of 6.0% during the forecast period. It is a potential pathway for patients with serious disease conditions to carry out treatment outside the trial when no satisfactory therapies are available. Increasing innovation in clinical trial methods is projected to drive the expanded access trials segment. For example, numerous oncology drugs are regularly administered to patients before their approval by the U.S. FDA and are considered part of the expanded access trial. Currently, there are 20 COVID-19 drugs in expanded access trials/compassionate use in Phase II/III.
Based on the Indication by Study Design Insights, the market is segmented into Autoimmune/Inflammation, Pain Management, Oncology, CNS Condition, Diabetes, Obesity, Cardiovascular, Others.
- The interventional trials market for autoimmune/inflammation accounted for the largest share with 82.0% in 2021. This can be attributed to a large number of interventional studies on autoimmune/inflammation worldwide. The growth can also be attributed to advantages of interventional studies, such as minimization of the effects of confounding, avoidance of bias in allocation to exposure groups, and efficient detection of small to moderate clinically important effects. There are over 7,000 interventional studies listed on clinicaltrails.gov related to autoimmune/inflammation.
- The observational trials market for autoimmune/inflammation accounted for the second-largest share in 2021. Out of the total autoimmune/inflammation studies listed on clinicaltrials.gov, more than 2,000 are observational. The expanded access segment accounted for the lowest share for autoimmune/inflammation in 2021.
Based on the Indication Insights, the market is segmented into Autoimmune/Inflammation, Pain Management, Oncology, CNS Condition, Diabetes, Obesity, Cardiovascular, Others.
- The oncology segment accounted for the largest revenue share with 23.5% in the global market in 2021. The segment is also anticipated to witness the fastest CAGR of 6.3% over the forecast period. As per U.S. FDA and various other sources, more than USD 38.0 billion is currently being spent by the pharmaceutical industry on the preclinical and clinical development of oncology therapy products. The cardiovascular condition segment is also anticipated to witness lucrative growth at a CAGR of 6.1% over the forecast period. The growing prevalence and increased demand for cost-effective medications worldwide have led to significant investment in R&D in this segment with more than 190 drugs in the pipeline.
- The majority of the drugs in the pipeline are indicated for heart failure, lipid disorders, vascular diseases, and stroke. Growing demand for cost-effective medicines in low- and middle-income countries is expected to boost the R&D investment by the government, thereby strengthening the market growth.
Based on the Sponsor Insights, the market is segmented into Pharmaceutical & Biopharmaceutical Companies, Medical Device Companies and Others.
- The report further provides a deep dive into the sponsors of the industry, wherein it was identified that pharmaceutical & biopharmaceutical companies accounted for the largest share with 70.0% in 2021. This can be attributed to the greater interest of the pharmaceutical industry in the research field. In addition, there has been an increase in the number of clinical trials funded by pharmaceutical & biopharmaceutical companies. The pharmaceutical industry plays a vital role in financing the research for the development of new drugs.
- Although grants from the National Institutes of Health (NIH) fund most of the basic research in academic laboratories, it is largely the industry that bears the cost of identifying new molecular entities and testing them on animal models and human subjects. Clinical studies account for the major portion of the estimated cost, ranging from USD 266 million to USD 802 million for bringing each new drug to the market. Currently, in the U.S., around 75% of all funding for clinical studies is received from corporate sponsors.
Clinical Trials Regional Outlook
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa (MEA)
Market Share Insights
- January 2020: Wuxi AppTec announced offering a fully integrated adeno-associated virus vector suspension platform to accelerate the development, manufacture, and launch of cell & gene therapy, thus expanding its service capabilities.
- June 2018: Acurian and Synexus, a part of PPD, wherein they launched SynexusPlus, a site solution for patient enrollment in clinical studies.
Key Companies Profile & Market Share Insights
The major factor influencing the competitive nature is the quick adoption of advanced technology for improved healthcare. In addition, to retain their market share and expand their product portfolio, major players are often involved in mergers and acquisitions as well as initiating new product launches.
Some of the prominent players operating in the global clinical trials market include,
- IQVIA
- PAREXEL International Corporation
- Pharmaceutical Product Development, LLC
- Charles River Laboratory
- ICON Plc
- PRA Health Sciences
- Syneos Health
- Eli Lilly and Company
- Novo Nordisk A/S
- Pfizer
- Clinipace
Order a free sample PDF of the Clinical Trials Market Intelligence Study, published by Grand View Research.


Comments
Post a Comment